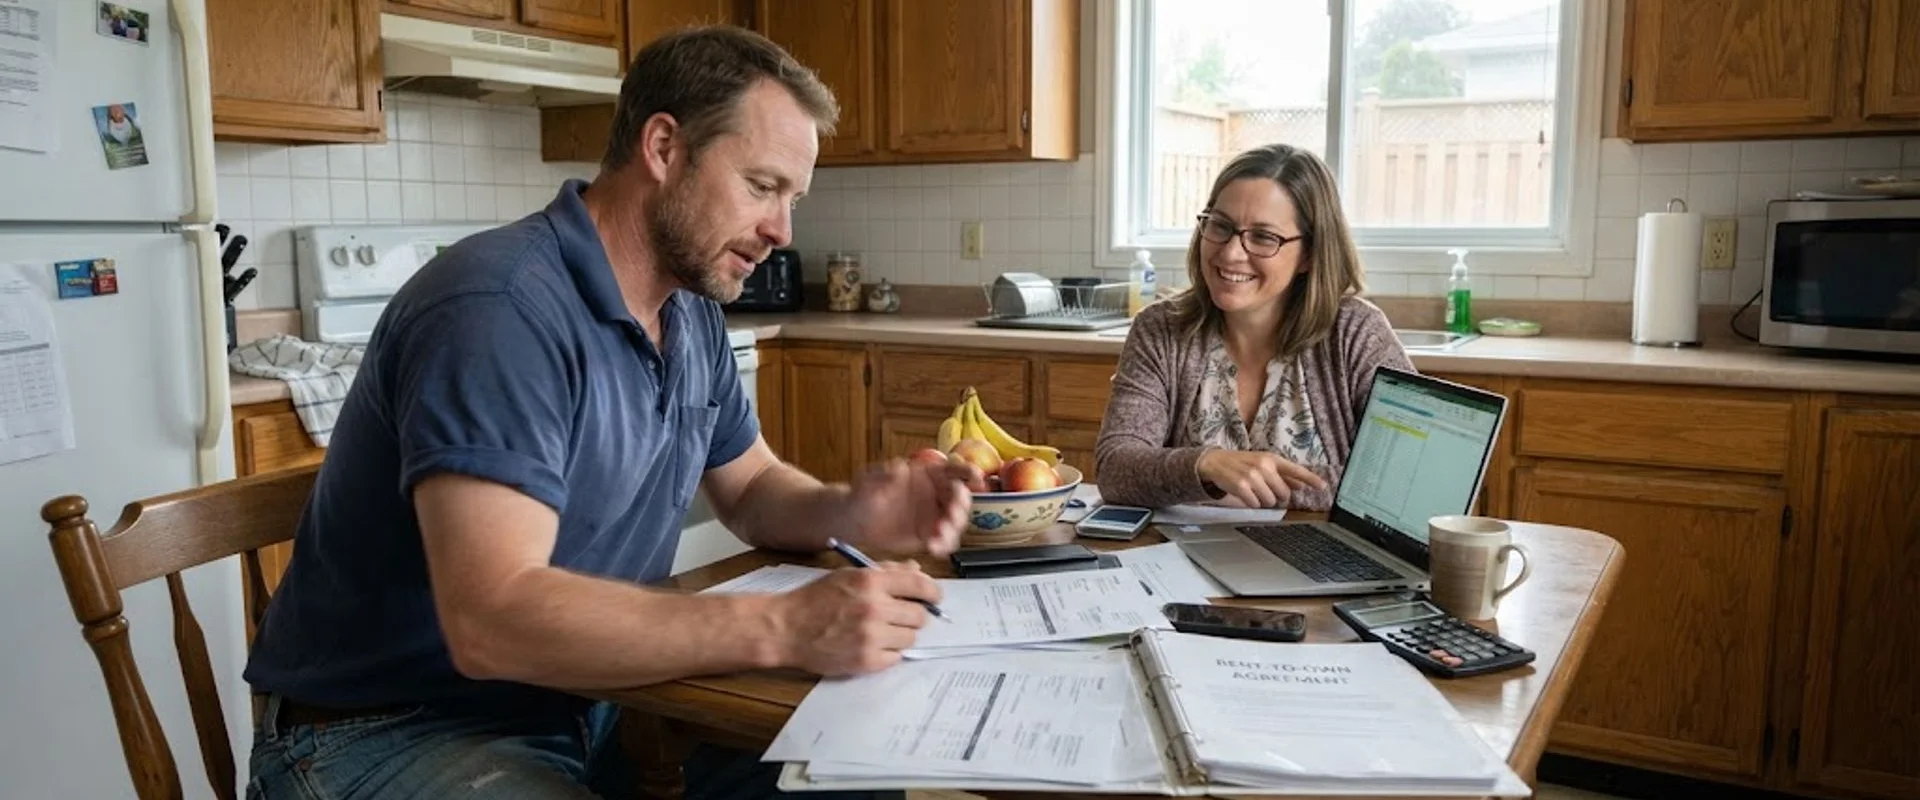
Bad Credit & Self-Employed Friendly in Ontario
Compare 29 Ontario rent to own providers that work with bad credit and self-employed buyers. Learn what to check and how our scoring helps.
Rent to own lets you move into a home now, pay rent plus a monthly premium, and buy it later at a price usually set up front. For buyers with bruised credit or income that doesn't fit a bank's template (contractors, owner-operators, commission earners), the draw is time: a year or three to rebuild credit and build a file a mortgage lender will accept.
The 29 businesses listed here say they work with these buyers. They don't all work the same way. Some own the homes and lease them to you. Others help you find a house, then fund the arrangement through investors. Ask which model you're dealing with before anything else.
What to look for
- How they verify self-employed income: bank statements, notices of assessment, or both.
- The purchase price, and whether it is fixed now or set at market value later.
- How much of your premium is credited toward the down payment, and what happens to it if you don't buy.
- A written plan for credit repair and a named mortgage partner.
- Who pays for repairs, property tax and insurance during the term.
Our scores weigh these points so you can compare listings on the same terms. See how we score for the full criteria. Have a real estate lawyer review any agreement before you sign.
Get matched with bad credit & self-employed friendly
Tell us what you need and we will connect you with suitable matches at no cost and with no obligation.
All bad credit & self-employed friendly, ranked by score and relevance
We found 29 businesses offering bad credit & self-employed friendly; 27 met the criteria for the scored directory. The order weighs each business's overall score by how much of its reviewed work is bad credit & self-employed friendly, so a lower-scored specialist can rank above a higher-scored generalist. Filter and sort below, or open the full map view.
Quote and contact requests you submit through our own forms may be passed to one or more partner providers who can carry out the work, and we may receive a fee for those referrals. Rankings and scores are not influenced by referral fees; they follow our independent, published scoring method.
Common questions about bad credit & self-employed friendly
- How much does a rent to own program usually cost up front?
- Most Ontario programs ask for an upfront option fee, commonly about 2% to 5% of the purchase price, plus first month's rent. Rent is typically above market, with the extra portion credited toward your down payment. Fees vary, so get every amount in writing.
- How long do I need to rent before buying?
- Terms usually run one to three years. Bad credit buyers often need most of that time to lift their score and show steady income that a mortgage lender will accept.
- What happens if I can't get a mortgage at the end?
- It depends on the contract. In many agreements you lose the option fee and any rent credits. Some providers extend the term or help you refinance. Ask for this clause before signing.
- How can I judge whether a provider is good?
- Look for clear written terms, a fixed or formula-based purchase price, refundable or credited amounts spelled out, and no pressure to sign fast. Have a real estate lawyer review the contract, and check the provider's score here.
Guides to choosing bad credit & self-employed friendly
- Preparing a rent-to-own application with bad credit
What to gather, what to fix and what to ask when your credit history is weak and you are applying for a rent-to-own program in Ontario.